
Circle, the issuer of the USDC stablecoin, has taken a central role in the conversation around the future of payments. With its recent public listing on the NYSE, the company has drawn renewed attention from institutional investors and policymakers alike. But beyond the headlines, Circle’s real impact lies in its transformation of how money moves—across borders, between platforms, and ultimately, across economic realities.
Circle in Context: Competitors and Market Positioning
Circle operates in a competitive arena alongside entities like Tether (issuer of USDT), PayPal (through PYUSD), and legacy banking infrastructures increasingly experimenting with tokenized money. Where Circle distinguishes itself is in regulatory alignment and transparency. USDC is fully backed by cash and short-term U.S. government securities, with attestations provided monthly. This focus has helped Circle gain credibility where other stablecoin providers have struggled under regulatory scrutiny or opaque backing structures.
While PayPal’s PYUSD aims to bridge digital payments and crypto, and Tether dominates volume in less regulated markets, Circle is carving a niche in regulated fintech and institutional adoption. As of its IPO week, Circle reported over $32 billion in circulation of USDC and expanded banking partnerships aimed at streamlining cross-border transfers【source: Reuters.
Stablecoins: A Payments Perspective
To understand Circle’s significance, one must see stablecoins not as cryptocurrencies, but as a new category of digital money. Unlike volatile assets like Bitcoin or Ether, stablecoins are pegged to fiat currencies—USDC, for instance, is tied to the U.S. dollar. This peg is enforced by reserves and transparency, enabling stablecoins to function as mediums of exchange, not speculative assets.
From a payments view, stablecoins offer:
Near-instant settlement, removing the lags and intermediaries of SWIFT transfers.
Low-cost cross-border flows, especially beneficial in regions with currency volatility or limited banking infrastructure.
Programmability, allowing for smart contracts and conditional payments in global commerce.
These qualities are what make Circle particularly interesting to payments professionals. As Jeremy Allaire, Circle’s CEO, said in a recent interview, “We’re not replacing the dollar; we’re giving it superpowers.” That framing captures the technological advance without invoking the kind of disruption narrative that often antagonizes regulators or incumbent institutions.
Innovation and Global Reach
Circle’s core innovation lies in marrying blockchain’s efficiency with regulatory clarity. Through partnerships with Visa and major banks, Circle is embedding stablecoin infrastructure into the mainstream financial system. Their new Cross-Border Treasury product offers multinational companies the ability to instantly fund overseas operations in USDC, bypassing correspondent banks entirely.
These capabilities are not theoretical. In Latin America, Africa, and Southeast Asia, stablecoins have already become the de facto rails for remittances and trade settlements. According to PYMNTS, emerging market fintechs are now actively integrating USDC into consumer wallets, driven by demand for dollar exposure and transaction reliability【source: PYMNTS】.
Stablecoins vs. Crypto: A Necessary Distinction
Unlike speculative crypto assets, stablecoins are built for utility. They do not promise high returns or volatility-driven gains. Instead, they provide consistency. This matters for merchants accepting international payments, for platforms that need to manage treasury in multiple jurisdictions, and for regulators seeking a balance between innovation and systemic risk.
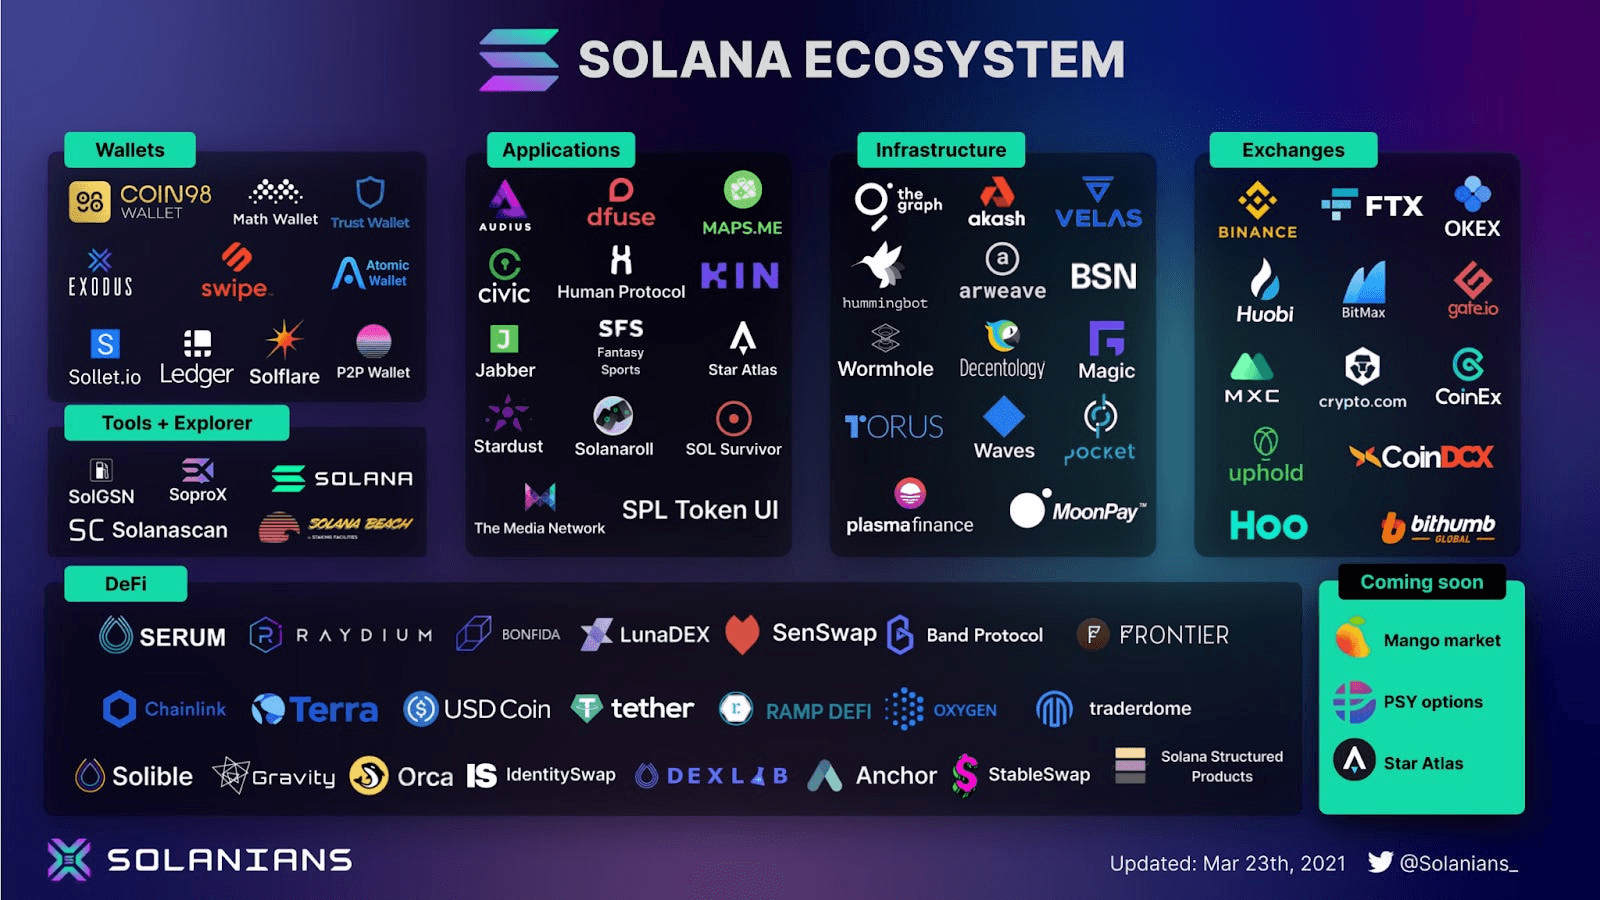
What makes USDC particularly potent globally is its interoperability. It can be held in non-custodial wallets, transferred on various blockchains (like Ethereum, Solana, and Avalanche), and redeemed one-to-one for USD. This gives users in countries facing inflation, capital controls, or unreliable banking systems a way to store and transmit value without entering traditional financial institutions.
The Future of Payments
Circle’s IPO is not just a capital event—it’s a signal that the infrastructure for global payments is shifting. As more institutions integrate with blockchains not to speculate but to transact, the border between finance and tech continues to dissolve. Stablecoins represent a middle ground: as regulated as money, as programmable as software.
But Circle’s success will depend on execution and trust. Investor excitement must be matched by operational resilience and continued regulatory approval. Volatility in the token markets around the IPO has shown that not all stakeholders are yet comfortable with this financial hybrid. Nonetheless, the path forward is increasingly digital, interoperable, and borderless—and Circle stands at its center.